

Lot sizing for a prop-firm evaluation should start with the cash amount you can lose if the stop is hit—not with a familiar lot size. The trade’s risk budget must sit below both your personal limit and the programme’s daily/maximum-loss rules, with room for spread, commissions and slippage. Pip or point value, contract size and the stop distance can differ by instrument and account specification.
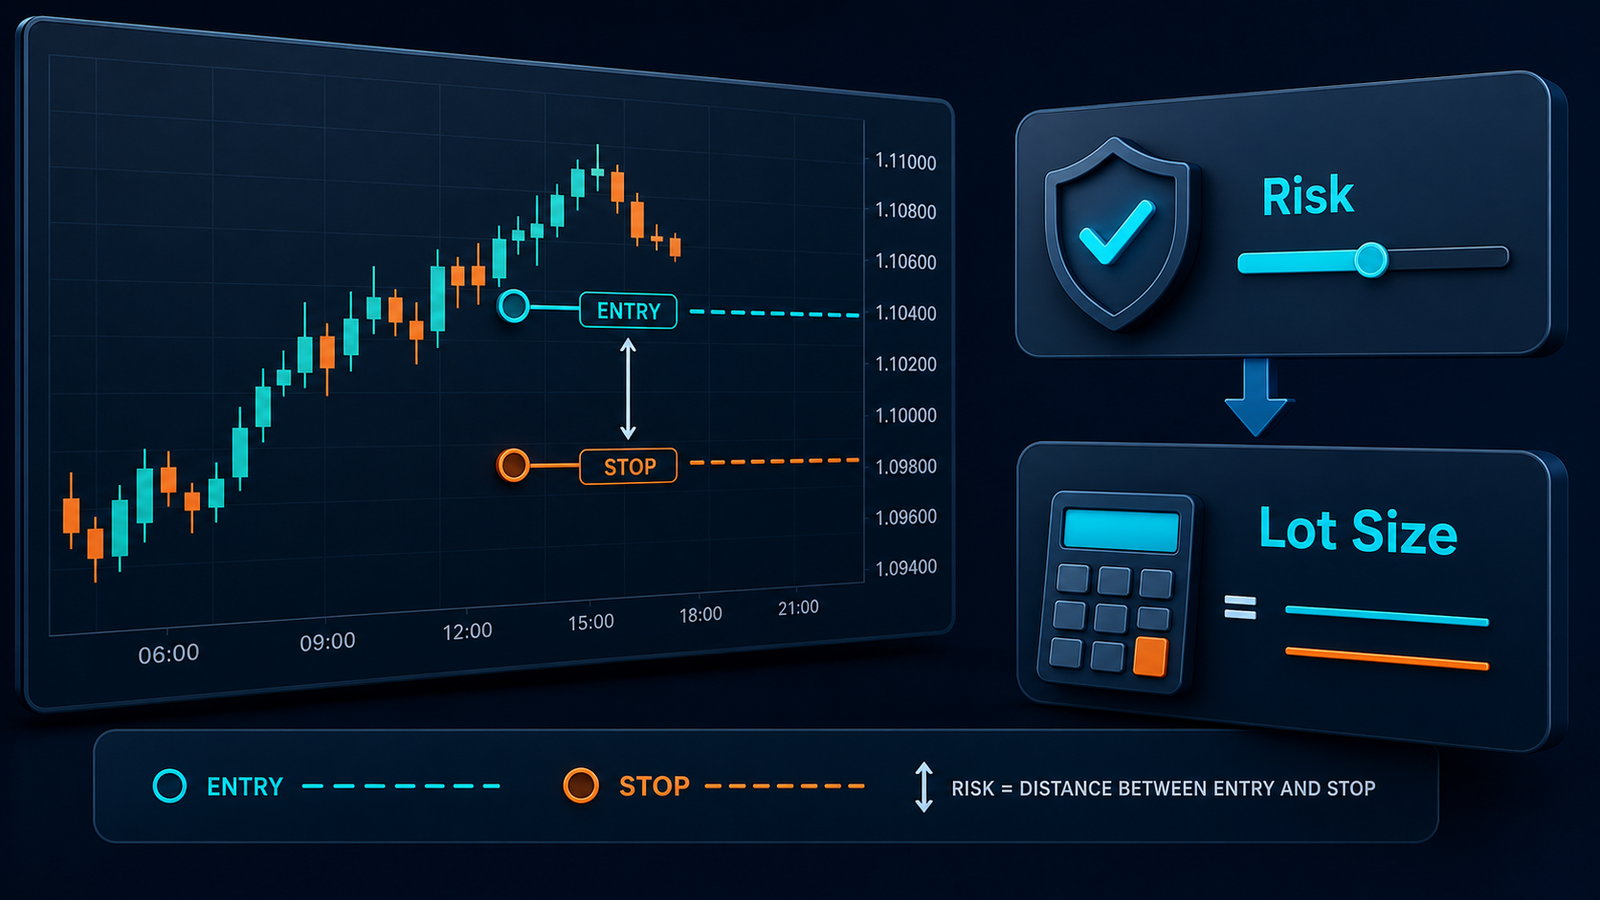
The position-sizing idea
Lot size = maximum cash risk ÷ estimated loss of one lot at the stop. To use that safely, obtain contract specifications for the exact instrument, account and platform. Forex, gold, indices and CFDs can use different units, contract sizes and values.
A five-step process
- Set a personal cash-risk limit for one trade; do not allocate the entire daily-loss room.
- Place invalidation from market structure and the trade idea, not to force an attractive lot size.
- Measure entry-to-stop distance in the correct pip or point unit.
- Estimate one-lot loss at that stop, including expected costs.
- Round down to the permitted increment and recheck exposure across correlated positions.
Hypothetical calculation
Suppose you accept a loss of 50 currency units on an idea. If one lot would lose about 100 units at the selected stop after estimated costs, the theoretical size is 0.5 lots before rounding. This is mathematics only; it cannot determine a size for gold or any symbol without verified contract specifications.
Why evaluations need extra room
An equity-based breach can occur before a stop fills as expected. Wider spreads, slippage, gaps, correlated trades and reset time are real sources of variance. A programme threshold is not a risk budget to spend; it is a contractual boundary.
Tools and related guides
Use the trading tools hub as a check, then read daily loss versus maximum loss, static versus trailing drawdown and the Trading Glossary.
FAQ
Should I use a fixed lot size in a prop-firm challenge?
Usually not. Stop distance changes between setups, so a fixed lot size makes cash risk inconsistent.
Does a calculator replace reading the rules?
No. A calculator needs correct inputs; the rules define the limits, equity treatment and account conditions.
Risk disclosure: This is educational information, not investment advice, a solicitation to trade or a promise of passing an evaluation. Prop-firm terms can change by programme, region and time. Trading can result in loss; verify official sources and your own risk limits.
Position sizing for a prop-firm evaluation
For an evaluation, position size should be derived from the smaller of your personal risk budget and the remaining programme buffer. The headline account size is often simulated capital; it should not be treated as money available to lose. First define the invalidation-based stop, then calculate the cash risk, convert the stop distance using the symbol’s contract specification, and subtract spread, commission, swap and a conservative slippage allowance.
For a simple FX example: cash risk = equity × risk percentage; position size = cash risk ÷ (stop distance × value per price unit). Pip/tick value, contract size, quote-currency conversion and volume step differ by symbol and provider. A formula that is correct for EUR/USD may be wrong for XAUUSD or an index CFD.
Chart-style worked example
| Field | Illustrative value | Check before order |
|---|---|---|
| Equity and personal risk | 10,000 USD and 0.25% = 25 USD | Does the programme buffer allow this loss? |
| Entry → invalidation | 1.0850 → 1.0825 | Is the stop where the thesis is wrong? |
| Stop distance | 25 pips before spread/slippage | Verify digits and pip value |
| Size | 25 USD ÷ cash risk per lot | Round down to the provider’s volume step |
| Post-order check | Record fill, spread and remaining loss room | Stop trading if the buffer is breached |
What can make the calculation fail?
- Wrong contract specification: pip, tick, point and contract size are not universal.
- Wrong account currency: the risk amount may need conversion.
- Oversizing after a win: a consistency or daily-loss rule can be breached even with a profitable trade.
- Ignoring open risk: correlated EUR/USD, GBP/USD and gold exposure can behave like one USD bet.
- Rounding up: minimum lot and volume step can push actual risk above the budget.
Do not trade when the stop is arbitrary, the symbol specification is unavailable, the required lot is below the minimum, or the remaining programme buffer is too small for normal spread and slippage. In those cases, reduce exposure, choose a different instrument or wait; do not force the calculation to fit.
Use the related general position-sizing formula, daily versus maximum loss, drawdown, risk–reward and glossary. Checked 16 September 2026. A useful primary reference is CME Group – Proper Position Size.
Failure, invalidation and no-trade
Failure case: Lot-size calculation fails when contract size, tick value, quote currency or actual stop distance is wrong. Invalidate the result when the platform specification cannot be verified. Do not trade when maximum loss at the stop, spread and slippage have not been calculated.