

A risk–reward ratio compares the amount a trader plans to lose if a trade is invalidated with the amount they may gain if the objective is reached. If a setup risks $100 to pursue $200, the planned ratio is 1:2, or 2R of potential reward for 1R of risk. The ratio is a planning tool, not a forecast: it does not measure the probability of either outcome, and a visually attractive target cannot rescue a setup with weak logic, poor execution or high costs.
Key takeaways
- Risk–reward is calculated from the entry, invalidation point and realistic objective—not from a preferred number chosen in advance.
- One R is the amount planned to be lost if the stop is executed as expected.
- A 1:2 ratio has a theoretical break-even win rate of 33.3% before spreads, commissions, financing and slippage.
- Planned R and realized R can differ because trades may be closed early, gap through a stop or incur costs.
- Risk–reward must be reviewed with win rate, expectancy, sample quality and market context.
What does risk–reward ratio mean?
The risk–reward ratio describes the distance or monetary amount between entry and invalidation relative to the distance or amount between entry and target. Traders often write it as risk:reward, such as 1:2. Some platforms and journals reverse the order and show reward:risk. Always check the convention before comparing statistics.
The word risk should refer to a defined trade invalidation, not simply a convenient stop distance. The stop belongs where the original trade idea no longer makes sense. This is why reading market structure and the broader price action context comes before calculating the ratio.
Risk–reward ratio formula
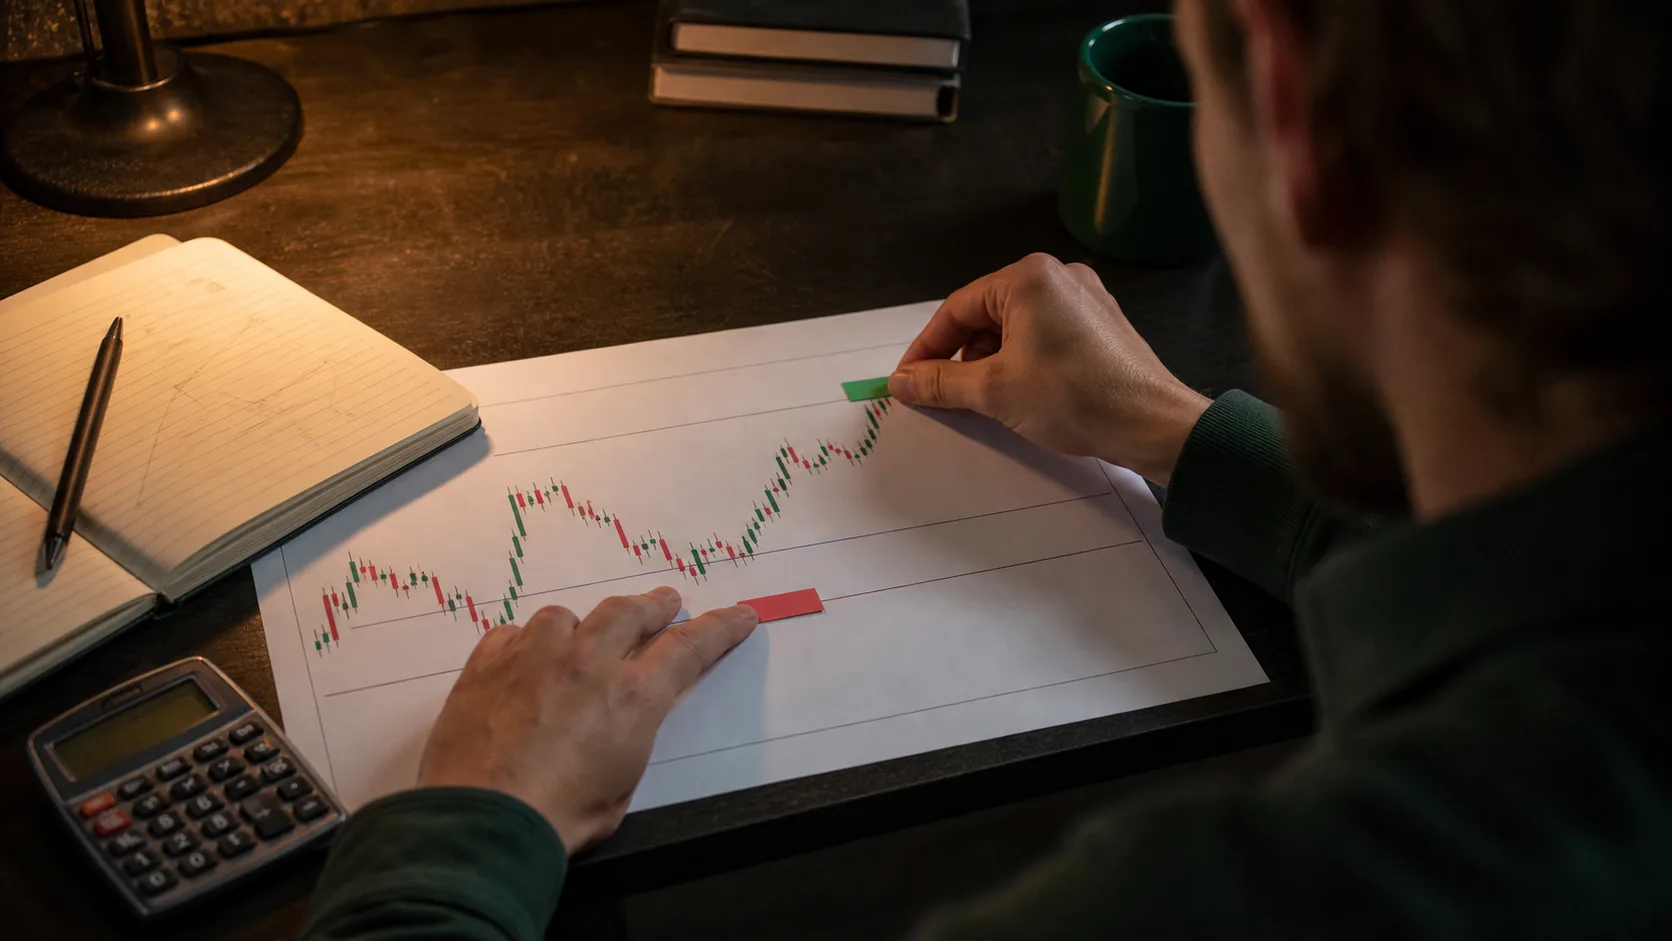
For a long trade, planned risk per unit is entry price minus stop price. Planned reward per unit is target price minus entry price. For a short trade, risk is stop price minus entry price, while reward is entry price minus target price.
Reward-to-risk multiple (R) = potential reward ÷ planned risk
Risk:reward notation = 1 : reward-to-risk multiple
Suppose a hypothetical long entry is 100, the invalidation is 98 and the objective is 104. Risk is 2 price units and potential reward is 4. The setup therefore offers 4 ÷ 2 = 2R, commonly written as 1:2 risk–reward. Position size does not change the ratio if the same entry, stop and target are used; it changes the money at risk. The position sizing formula is a separate calculation that converts the stop distance into money at risk.
How to calculate risk–reward step by step
- Define the setup. State what market condition or pattern must be present.
- Choose the entry rule. Use the price that can realistically be executed, not the best price visible after the fact.
- Set invalidation. Identify where the trade thesis is wrong, then place the planned stop with execution risk in mind.
- Choose a defensible objective. Use structure, liquidity or a tested exit rule rather than forcing a round multiple.
- Measure risk and reward in the same unit. Price, points, pips or money all work if used consistently.
- Deduct expected costs. Spread, commission, financing and slippage reduce the realized result.
- Record planned and realized R. The difference reveals execution and behavior problems.
A target should also respect where orders may cluster. The guide to liquidity in trading explains why a distant objective can look attractive mathematically but remain unlikely within the current structure.
Break-even win rate and risk–reward
Break-even win rate is the win rate required for gross gains to equal gross losses when average wins and losses match the planned R multiple. Before trading costs, the formula is 1 ÷ (1 + reward-to-risk multiple).
| Risk:reward | Reward multiple | Theoretical break-even win rate |
|---|---|---|
| 1:1 | 1R | 50.0% |
| 1:1.5 | 1.5R | 40.0% |
| 1:2 | 2R | 33.3% |
| 1:3 | 3R | 25.0% |
| 1:4 | 4R | 20.0% |
These are arithmetic thresholds, not expected results. A strategy targeting 3R may win less often than one targeting 1R because the target is farther away. Costs also raise the required win rate. If a nominal 2R winner nets only 1.85R after costs while a losing trade averages –1.05R, the simple 33.3% threshold no longer applies.
Planned R versus realized R
Planned R is the outcome map before entry. Realized R is the actual profit or loss divided by the initial planned risk. A trade planned for +2R may finish at +0.6R if it is closed early, while a stop can exceed –1R during a gap or fast market.
| Event | Possible effect | Journal question |
|---|---|---|
| Spread widens | Entry or exit becomes less favorable | Was the cost normal for that session? |
| Slippage at stop | Loss may exceed 1R | Was liquidity thin or an event near? |
| Partial profit | Average winner changes | Was scaling part of the written rule? |
| Early discretionary exit | Reward may shrink | Was the thesis invalidated or did fear intervene? |
| Trailing stop | Outcome distribution changes | Is the trail tested as part of the system? |
Worked hypothetical examples
Example 1: a clean 1:2 plan
A hypothetical setup risks $75 and has a realistic objective worth $150 before costs. Planned reward-to-risk is 150 ÷ 75 = 2R. If the stop is filled as expected, the result is approximately –1R. If the full target is filled, the gross result is +2R. This example demonstrates the units; it is not a trade recommendation.
Example 2: the ratio looks good but context is weak
A trader sees a possible 1:4 ratio by placing a target far beyond the nearest opposing structure. The chart is in a narrow range, participation is low and the target would require an unusually large move. The arithmetic is correct, but the assumption behind the reward is poor. Checking a multi-timeframe analysis may reveal that the proposed target conflicts with higher-timeframe conditions.
Example 3: correlated positions hide total risk
Three trades may each show 1:2 and risk 1R, yet all may depend on the same currency or market theme. If they fail together, portfolio exposure can be close to 3R rather than three independent 1R bets. Per-trade risk–reward does not replace a total exposure limit.
Why a favorable ratio does not guarantee a good trade
Risk–reward contains no probability estimate. Expectancy depends on how frequently wins and losses occur, their average size, costs and whether the sample represents current conditions. A strategy can lose money with a planned 1:3 ratio if targets are rarely reached or losses regularly exceed the stop assumption. A 1:1 strategy can have positive expectancy if its net win rate and execution remain strong enough.
Time also matters. Volatility, liquidity and spread vary across trading sessions. A fixed target that is reasonable during an active overlap may be unrealistic during a quiet session. The ratio should follow the setup and market behavior, not dictate them.
Common risk–reward mistakes
- Forcing every trade to 1:2 or 1:3. The market does not owe a preset multiple.
- Moving the stop closer to improve the ratio. A tighter stop can sit inside normal price noise and change the trade thesis.
- Ignoring spread and slippage. Small stops are especially sensitive to execution costs.
- Using the target as a prediction. A target is a decision point, not proof that price will arrive.
- Comparing gross winners with net losers. Use one consistent basis after costs.
- Changing exits mid-trade without a rule. This makes historical R statistics hard to interpret.
- Evaluating one trade. Risk–reward becomes useful when reviewed across a meaningful sample of the same setup.
A practical risk-management checklist
- Is the invalidation based on market logic?
- Is the target reachable within current structure and volatility?
- Are entry, stop and target measured in the same unit?
- Have normal and stressed transaction costs been considered?
- Does position size keep the monetary loss within the written plan?
- Are correlated positions included in total exposure?
- Will planned R and realized R be recorded separately?
If a strategy is still being learned, use historical review or a demo environment before risking capital. The guide on practicing a trading method without real money offers a process-first example that can be adapted to other setups.
Risk–reward, win rate and expectancy
Expectancy combines the frequency and average size of wins and losses. A simple net expectancy model is: (win rate × average net win) – (loss rate × average net loss). Risk–reward contributes the outcome size, but it does not supply the win rate. Both estimates need data from the same rules, instrument group and exit method.
Consider two hypothetical systems. System A wins 60% of trades, averages +0.8R on winners and –1R on losers. Its gross expectancy is (0.60 × 0.8) – (0.40 × 1) = +0.08R. System B wins 35%, averages +2R and loses –1R. Its gross expectancy is (0.35 × 2) – (0.65 × 1) = +0.05R. The higher planned reward of System B does not automatically create a larger edge. Costs or behavioral execution could make either result negative.
Do not combine incompatible samples. A 2R target tested on one-hour trend setups should not be validated using results from five-minute range trades. Segment journal data by setup, exit rule, instrument and relevant market regime. This makes the estimated relationship between R and win rate more interpretable.
Partial exits and trailing stops
Scaling out changes the average payoff. If half a position exits at +1R and the remaining half reaches +3R, the gross weighted result is +2R before costs. If the second half returns to break-even, the result is only +0.5R. Calling both trades “1:3 setups” hides the actual distribution.
A trailing stop also creates a range of outcomes rather than one fixed reward. That is not inherently better or worse, but it needs its own evidence. Compare the full distribution of realized R, including small wins, scratch trades and losses, instead of judging the method by its largest winner.
How to validate a risk–reward rule
- Write an objective entry, invalidation and exit rule before viewing the outcome.
- Collect a sample large enough to include different conditions without mixing unrelated setups.
- Record gross and net realized R, including every cost.
- Measure win rate, average win, average loss, median result and adverse execution differences.
- Separate rule-following trades from deviations so behavior is not mistaken for strategy quality.
- Use out-of-sample or forward testing to check whether the relationship persists.
- Define in advance what evidence would justify changing the rule.
Testing cannot guarantee future performance. Its purpose is to replace a preferred ratio with an observed range of outcomes and clearly stated uncertainty.
Frequently asked questions
Is 1:2 always a good risk–reward ratio?
No. A 1:2 ratio only describes planned payoff geometry. It is useful when the stop and target are logical and a tested sample shows that the setup reaches its outcomes often enough after costs.
Should the stop be changed to get a better ratio?
The stop should be tied to invalidation. Moving it solely to improve the displayed ratio can place it inside normal market movement and reduce the setup’s probability of surviving noise.
Does risk–reward include position size?
The ratio can be measured per unit without position size. Position size converts the stop distance and instrument value into money at risk. Both must be planned before entry.
Sources and methodology
- CME Group: Risk Management and Your Trade Plan, accessed July 16, 2026.
- CME Group: Proper Position Size, accessed July 16, 2026.
- CFTC: Eight Things You Should Know Before Trading Forex, accessed July 16, 2026.
Risk warning: This article is for education and general information only. It is not investment advice, a personalised recommendation or an invitation to trade. Trading involves the risk of losing capital, and leverage can amplify losses. Past results do not guarantee future outcomes. Research independently, assess your risk tolerance and take responsibility for your decisions.